Showing posts with label stocks. Show all posts

Tuesday, 2 April 2024

My 7-Figures $x,xxx,xxx Porfolio (2024 Q1)

I received quite alot of comments and requests from my previous post $983k profits in 20 years (2005-2024), and decided to refresh my portfolio for the end of Q1 2024. Due to my conservative nature, I hold close to 18% of bonds (Tbills, SSB and yes even some old Astrea 6/7 bonds). UOB has grown steadily to become the largest bank in my portfolio, as I couldn't resist nimbling at it due to its price weakness vs the other 2 local banks. With the hope of interest rate cuts soon, I chose MLT, the weakest of the strong Reits and increased my position to 3%. I probably should have been more aggressive to buy up on the S&P500 ETFs, and instead of accumulating more I instead sold some, as I had expected a pull-back before S&P500 index would break with new all-time highs. Tsk tsk, an error in my judgement, not to trade what happened but what I forsee would happen... 😅  Let me know if u have any comments on how I should improve my portfolio, thanks!


Banks currently form my largest portfolio with around 37%. The 3 local banks have been  the prime gainers of high interest rates, posting record profits and great dividends too at almost 6%. With these high dividend yields does it still make sense to invest in Reits?! Still interest rates are not going to remain high forever, and Reit prices are badly beaten down. There should still be more tough financial quarters ahead as higher interest rates eat into Reits balance sheets. Well, can always start nimbling abit ... 😂  I have basically left Others & Blue Chips (Keppel, Wilmar, Comfort, Singtel, SIA) alone to balance and diversify my portfolio. They have their fair share of trying to refresh their businesses to suit the ever changing competition and financial environment. So this basically sums up my humble portfolio! Hope it benefits u or your curiosity 😎

Press on, you Mighty Man of Valour!


Saturday, 17 June 2023

AA Reit Rights at $1.189


AIMS APAC (AA Reit) has launched a Preferential Offering/Rights of 35-for-1000 at $1.189 to existing shareholders. Being a small long-time existing shareholder of AA Reit, I am quite surprised that the rights is offered at such a low price. As expected, market sold down unfavourable on this preferential offering news, to even $1.16 below the rights price (close to 1 year lows of $1.13)


With some heavy selling seen even below $1.18, this would be an even cheaper price than the preferential offering price+comission fees if bought over the market. At one point, I was even considering buying from the open market and forfeiting my rights instead. Unfortunately or fortunately 😎, prices recover on Friday to close at $1.22


I had been considering to purchase more AA reit for some time in AA reit at $1.3 a good Buy? as I generally consider this as a reasonably small but well managed Reit (vs MIT/MLT/Areit) with prices ranging between $1.2-$1.5 for the past few years, for a reasonable yield of between 6-8%

I would be subscribing to this preferential offering and probably oversubscribing more to round up to 1k shares for long term investments. Hopefully this decision would turn profitable in time to come, both in terms of dividends and capital gains

Would u be subscribing to this preferential offering or what are some of your thoughts on AA reit? Pls feel free to share in the comments below  😊

Friday, 9 June 2023

Wow Sembcorp Ind at $5.50!


Finally Sembcorp Industries (SCI) is at its 10 year highs of $5.50, an incredible strong run over the past 2-3 years from a government linked company. It's almost unimaginable that such a blue chip stock, would have a price increase that is only typically seen in a much smaller size growth enterprise

See also:

With price levels above $5, various research houses have been busy evaluating again what should be the real target price of SCI moving forward. I have been steadily taking profit at my long time investment and unfortunately only have a small position left, as I did not purchase much during the distressed price in 2020


While it is true that SCI have divested the cyclical business of Sembcorp Marine (SMM) for the better, such a phenomenal price rise still seems too good to be true. With current hot news on climate change and renewables, SCI does seem to be in a good business to concentrate for the future.


Hmm... should I continue to sell into new price highs, or just trail the yellow moving average MA10, or just wait further for psychological level of $6!  😂  Let me know in your comments below

Thursday, 8 June 2023

MIT 3rd Largest Tenant Cyxtera gone Bankrupt!


As mentioned in my previous post on Headwinds for Mapletree Industrial Trust (MIT):

This news has now been announced with MIT's 3rd Largest Tenant Cyxtera Technologies entering the Chapter 11 Bankrupcy process

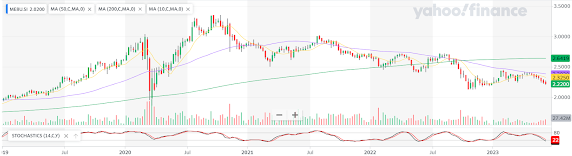
Cyxtera has contributed 3.2% of gross rental income for MIT as at 31 March 2023. While blue chip MIT boasts of a well-diversified tenant base, this negative news would inadvertently be a drag to its share price


With prices closing in to short-term Oct22 lows of $2.13 and long-term Covid Mar20 lows of $2.10, hopefully these price supports would hold the sellers at bay.

Bearish trend continues with the purple weekly MA50 sloping downwards and even acting as a resistance point in Apr23.

Other affected reits included Digital Core and Keppel DC, all putting up brave fronts to soothe shareholder sentiments.

It only goes to show that with new seemingly lucrative Data Centre businesses, risks do abound with every new investments that are outside of traditional property strengths of Reits.

Also with rising and persistant high interest rates, MIT and Reits being highly leveraged companies, will continue to face strong headwinds in the months ahead.

What are some of your thoughts of MIT moving forward? Let me know in the comments section below

Disclosure: I am currently vested in MIT  😅


Wednesday, 19 April 2023

Will Kepcorp at $6.2 go HIGHER?


Keppel Corporation is a government linked company with strong capabilities in energy & environment, urban development and connectivity. Many Singaporeans will be much familiar with this grandfather stock

Kepcorp has a market capitalisation of $11B with a 52wk price range of $4.57 to $7.72 (current price at $6.21) which is -20% from 52w high and +36% from 52w low

Throughout the many years, Kepcorp has rewarded shareholders with relatively good dividend (2-6%), even during Covid year of 2020


In the short term, psychological $7 and $7.50 resistance levels will be the prices to watch. Also not forgetting $7.35 which was the price that Temasek initially offered to buy Keppel private, before calling it off. So lots of resistance bands ahead.


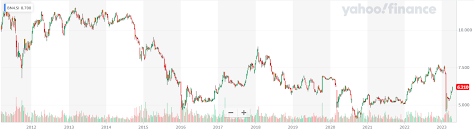
Looking at the long term chart, it's probably hard to recall before 2014, that Keppel used to be a $10+ stock. Those are probably the good old days where shipbuilding was lucrative and profitable before the Chinese shipyards competition kicked-in


With the sale of its Oil&Gas segment to Sembcorp Marine, the problematic & cyclical profit sector seems to be unhinged from the future dreams of Kepcorp. It is now ready to embark on a more asset light management moving forward. With gahment ambitions on-the-tow, will it be able to make further inroads into neighbouring Asia and Asean countries? I certainly hope so, as I am currently vested  😂

Monday, 3 April 2023

Is RMG at $1.49 a good SELL?


Raffles Medical Group (RMG) is a private healthcare provider in Asia, operating in Singapore, China, Japan, Vietnam and Cambodia. It has a network of clinics with family physicians, specialists and dental surgeons, and owns Raffles Hospital, a tertiary care hospital in Singapore, which accommodates surgical centres, medical laboratories and 24 specialist centres in various areas like Obstetrics & Gynaecology, Cardiology, Oncology and Orthopaedics.


RMG has a market capitalization of around $3B and the latest FY22 results have been reasonably good. Revenue grew by 6% to $767M and profit grew by 72% to $144M. Earnings per share grew 72% to 8c, while Net Assets Value grew 6% to 55c. A final divdend of 3.8c has been declared and will xd on 9 May.


Taking a closer look at its P&L, shows the strong increase in profit came mainly from a sharp drop in Staff costs ($45M) and Inventories and consumables used ($21M).


From the long term chart, RMG price has performed very well, growing from $0.2+ in 2009 till around $1.5 in 2016 and 2023. There were two attempts to break $1.5+ range n 2015-2016 before succumbing to profit taking to $1. Then Covid struck in 2020, and the price is again attempting to break $1.5+ resistance level.


Moving Average MA50 seems to be sloping up and supporting to push price upwards. Volume is slightly above 20days average. Stochastic oscillator is also trickling up  to the overbought region. All-in-all, Technical Indicators do not seem to point to a strong punch through resistance level of $1.5+

Singapore & China reopening from Covid, could push its financials better in the year ahead.

What do u think? Let me know in your comments below 😍

My 7-Figures Singapore Portfolio


My portfolio has been painstakingly built over 20 years of investing. It is far from perfect and there could also be some glaring mistakes seen in my portfolio made years ago. After publishing below blog post, some readers have requested to share my 7-figures portfolio

To do my small part in contributing to the Singapore investing community, here goes 😅:


As a relatively conservative investor, the largest component of my current portfolio is Fixed Income Bonds, consisting mainly of 6/12 months T-bills, SSB, Fixed deposits and Temasek/Astrea Corporate Bonds. 

Next are the 3 local banks, which I picked up over the past few years. Would have loved to purchase more for a bigger % of my portfolio, but they have risen so much over the past year. In the past, I tend to avoid bank stocks, as I felt they are important yet boring companies. However as I age (more risk averse 😆) and analyze them further, they truly have solid investment moats in Singapore and very strong financial fundamentals. 

Mapletree Industrial Trust is a good Reit, strong sponsor with nice increasing dividends. I probably picked it up at a slightly higher price, on anticipation in the growth of its newer Data Centres purchases. With current weakness in Technology and rising interest rates, MIT prices have retraced somewhat.

Comfort Delgro seems to be a good proxy of the Covid reopening with packed MRT trains nowadays. But the lucrative taxi market have been carved away by Grab/GoJek private hires. Hope it continues to pay good dividend. Some patience is probably needed here.

Wilmar is a solid commodity company, which I have shared previously. Currently it seems to be shrugging off negative Adani news and edging slowly but surely up. Hope there's more price upside 😎

Everyone should be familiar with Singtel, as it used to be the largest company in Singapore. The banks have now overtaken its market cap position. Lucrative overseas calls have been replaced through technology like whatsapp/zoom etc. Industry players are also left wondering what is the next killer app for 5G. 

Oil & Gas companies (SMM and Kepcorp) used to be darlings of the 'black gold' market. Fierce competition from Chinese/Korean shipyards have eroded their profits. Hopefully with the recent merger of SMM+Keppel O&G, will we see better days ahead. 

This ends my humble sharing of Top10 portfolio. Hope it encourages u to press-on in your investing journey. Please feel free to comment below if u have further questions 😂

Friday, 31 March 2023

Is AA Reit at $1.3 a good BUY?


Listed on the Singapore Exchange Securities Trading Limited ("SGX-ST") since 2007, AIMS APAC REIT’s ("AA REIT") objective is to invest in a diversified portfolio of high quality income-producing logistics, business parks and industrial real estate throughout Asia Pacific.


AA Reit's current market capitalization is around $1B, and boasts of 29 properties in Singapore/Australia with $2.4B of total assets. Most notably is the large purchase of Woolworths HQ in Australia, which is starting to contribute to the Reit's revenue.


The long term stock price has been hovering around $1.3 since 2013, with the exception of price weakness down to $1 in 2020 due to Covid outbreak.

With the latest quarterly dividend of 2.59c, we are looking at a forward yield of almost 8% at $1.3


For the past 12 months, AA reit stock price has been fairly resilient between the range of $1.11-1.44, despite pressures on rising interest rates and USA/Swiss bank failures. It is now 8% away from its 52 weeks high and 19% from its 52 weeks low.

With the fast rise of interest rates behind us, and looking to a more flat or even decreasing interest rates in 2023, would the 8% yield entice investors to buy this Reit?

Pls let me know in your comments below. 

*Disclosure: I am currently vested in AA Reit

Sunday, 5 March 2023

Is SCI at $3.71 a good SELL?


Sembcorp Industries is a govt-linked energy and urban solutions company with a market cap of $7B. With the latest good FY22 results of $848 net profit, they have proposed a 4c+4c final+special dividend (FY dividend yield 3.2%). After divesting its interests in Sembcorp Marine, it has climbed steadily from the past 3 years to $3.71


It is currently hovering close to its recent 52w high of $3.83, with some sellers eager to divest for profit.


Will it be able breakthrough this price resistance level to achieve $4? Please help to comment below 😎

*Disclosure: I am currently vested in SCI

Friday, 3 March 2023

Is Wilmar at $3.94 a good BUY?


Wilmar is one of the largest companies in Singapore with a market capitalisation of $25B. With a record FY22 net profit of US$2.4B and upcoming increased dividend payout of 11c, its price however has been under pressure these days. Mr Kuok, the Chairman and CEO of Wilmar even had to support its price this week, as the stock succumbed to $3.87 from heavy selling. 


From the Covid correction in Mar 2020, its price has rebounded from $3 to $5.3 in Mar 2021, only to retrace till its current $3.94 price. With a dividend of 17c, this translates to a 4.3% yield (slightly higher than current SSB, T-Bills and Fixed Deposits).

The price weakness could be due to management expectations of a challenging FY23 with plantation profits under pressure but mitigated by China reopening from zero-Covid policy.


Taking a longer term view on price: Wilmar used to be $6+ in 2010, before consolidating to form a solid base of around $3 in the years of 2013-2019.

Would these base years of company restructuring into a solid commodity company translate to a stronger price in the near future?

Please feel free to leave your comments below

*Disclosure: I am currently vested in Wilmar